Roof Insurance Claims in Broken Arrow, OK
You'll know what's up on your roof, and have it on record with a date, before you decide whether an insurance claim is worth opening. Leave the address and the storm you have in mind, and our roofers photograph it plane by plane and call you about what they found.
The two Oklahoma clocks on a wind or hail claim
A storm's been through, somebody has used the word claim, and you're weighing a deadline you haven't read against a deductible you'd spend to find out if anything's wrong. None of it has to be decided before you know what the roof took.
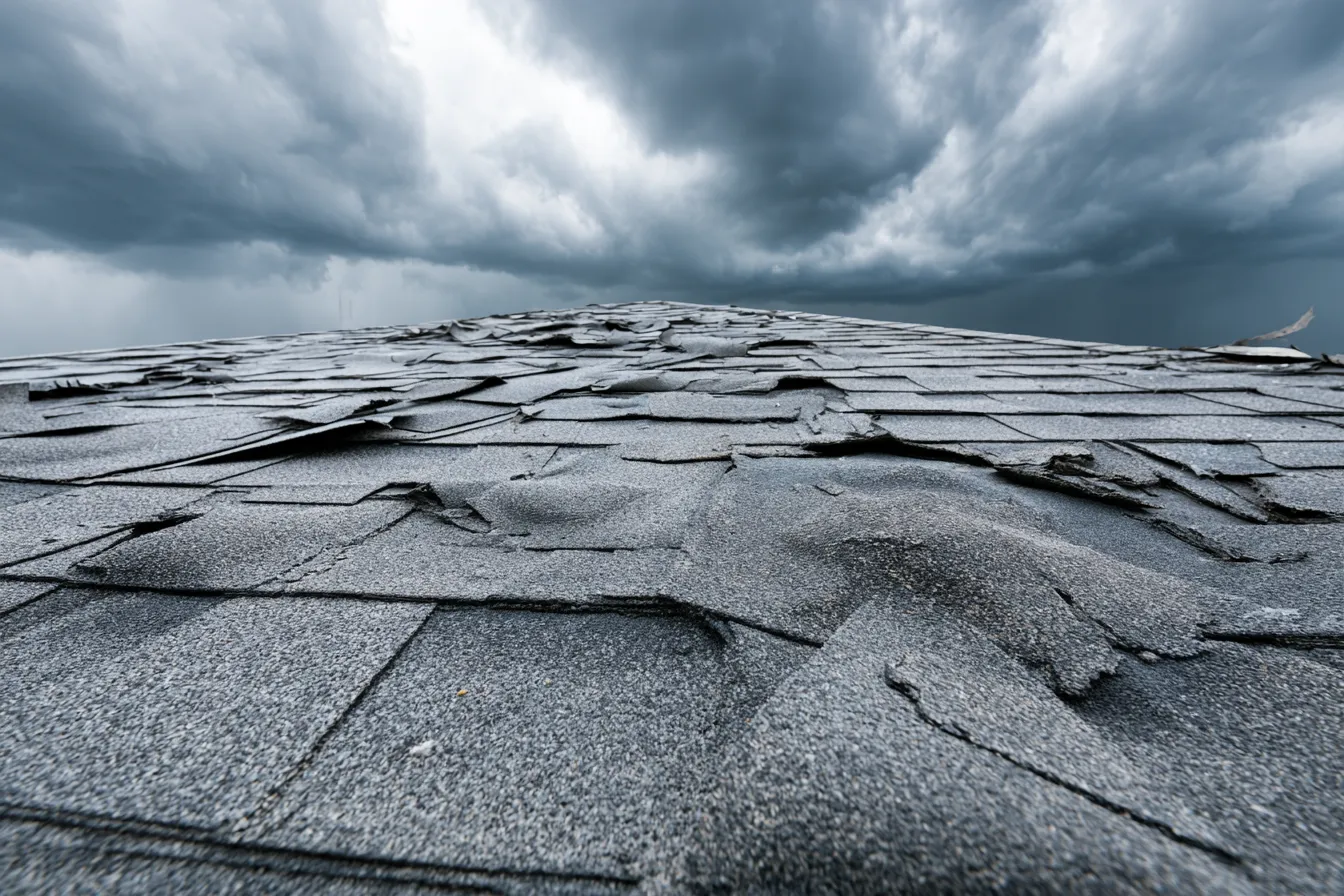
A house off Elm Place can come through a May hail night looking untouched and stain a ceiling that winter. That's the case Oklahoma keeps two clocks for. Your policy likely gives you about a year to report it, and state law won't let a policy close a wind or hail claim at that first year when only an inspection would have found it: that one stays open as far as 24 months. Which clock you're inside turns on what was visible and when, so ask Broken Arrow Roofing Co for the inspection that dates it and keep the report.
What your policy decides before an adjuster arrives
Two houses can take the same hail on the same afternoon and come out of a claim in very different places, because most of that difference was written into the policy years before the storm. Tulsa County's record over the last four years carries 30 separate hail days, so more than one storm is usually in the frame. What follows is already decided in a document you own.
- Actual cash value or replacement cost: one pays an older roof what age has left it worth, and the other pays what a new roof costs today.
- Recoverable depreciation: on a replacement cost policy the carrier holds part of the money back, and it only comes loose once the work is finished and invoiced.
- The wind and hail deductible: many Oklahoma policies figure this one as a share of what the house is insured for instead of a flat amount, which moves your side of it a long way.
- Functional damage or cosmetic: policies draw a line between hail that broke the shingle mat and marks that only changed how a roof looks, and the wording for that line is in yours.
- The age of the roof: some policies carry an endorsement paying an older roof only a share of replacement, and where one is in force it overrides the replacement cost wording.
None of those five happen on the roof, and none of them are your roofer's call. What our roofers add is the other half: the planes walked, the flashing and the boots looked at close up, and photographs carrying the date, which is what a roof inspection is here. Dates matter here as much as damage does, and what a county hail record can and cannot tell you gets into why. Your own agent is the one to take you through the policy half.
The claim words that decide your payout
Once a claim is open the paperwork starts leaning on a handful of terms, and each one changes what lands in your account. None of them are hard once somebody puts them in ordinary words.
Every carrier words these its own way, and the wording in your own policy is the one that counts.
What Broken Arrow homeowners ask before they file
These come up in the week after a storm, before anybody has filed anything. Where the answer turns on your own policy wording, it says so.
Q1What are the two deadlines on an Oklahoma roof claim?
Q2Does a roofer file the claim for me?
Q3What if the adjuster's estimate leaves something out?
Q4I've never filed a claim and I don't know any of these words. Is that a problem?
Q5A roofer offered to cover my deductible. Is that allowed?
Q6Is it worth filing if the damage looks minor?
Start with the evidence.
Your roofer photographs the planes, puts the date on each one, and calls you about what they found before anything is filed. Our roofers work with your adjuster on what the roof shows, and the report is yours to keep.